Arts

Home Arts Page 7

Binance Faces EU Service Curbs as MiCA Deadline Nears

0
Binance Faces EU Service Curbs as MiCA Deadline Nears


Binance will restrict certain services for users in the European Union (EU) starting July 1, 2026, after the world’s largest crypto exchange failed to secure a MiCA license before the regulation’s transitional period ends. This development comes after Binance withdrew its license application in Greece, stating that user assets remain safe and accessible, and that some EU accounts will be affected depending on their country and account status.

Binance’s MiCA Setback

In an announcement on June 24, Binance confirmed that it had withdrawn its MiCA license application with the Hellenic Capital Market Commission (HCMC), Greece’s capital market regulator. The exchange said the decision was made after considering the progress and timeline of the licensing process in Greece, and stated that it would pursue a license in another EU member state.

Binance emphasized that it had not received a “formal decision” from the Greek regulator as the MiCA transitional period nears its end. Previously, in a June 16 update, the exchange said it had submitted a complete application, worked with the HCMC for months, and understood that the application was being reviewed at the ESMA level following the evaluation process in Greece.

The withdrawal leaves Binance unable to obtain a MiCA license ahead of the July 1, 2026, deadline. Article 143 of Regulation (EU) 2023/1114 allows existing crypto-asset service providers to operate during a transitional period until that date, or until their application is granted or refused, whichever comes first.  

As of ESMA’s June 26 update to its MiCA register, Binance does not appear on the list of authorized crypto-asset service providers.

The Financial Times reported that the application in Greece faced hurdles related to anti-money laundering controls and “fit and proper” standards, including the role of founder Changpeng Zhao. Binance did not confirm this characterization and stated it had not received an official decision from the HCMC. Without a MiCA license, Binance will not be able to continue providing its full range of services in the EU as an authorized provider after the deadline.

What EU Users Can Expect

Binance stated it is contacting affected EU users directly and will specify whether individual accounts require action, the available options, the relevant timeline, and support channels. The exchange said user assets remain “safe and secure” and accessible, while warning that Binance will not call to request passwords, 2FA codes, or private keys.

The specific extent of the impact by service and country has not been fully disclosed by Binance. In a June 24 blog post, the exchange only stated that some users could be affected depending on their country and account status, and has not provided an official list of which services will be halted, restricted, or remain active in each EU market.

According to Reuters, the Spanish stock market regulator, CNMV, has ruled out extending the MiCA crypto licensing deadline. Platforms that are not licensed after this deadline will not be allowed to solicit new clients or continue providing regular services, except for activities necessary to reduce or close positions, transfer assets, or support an orderly wind-down process.
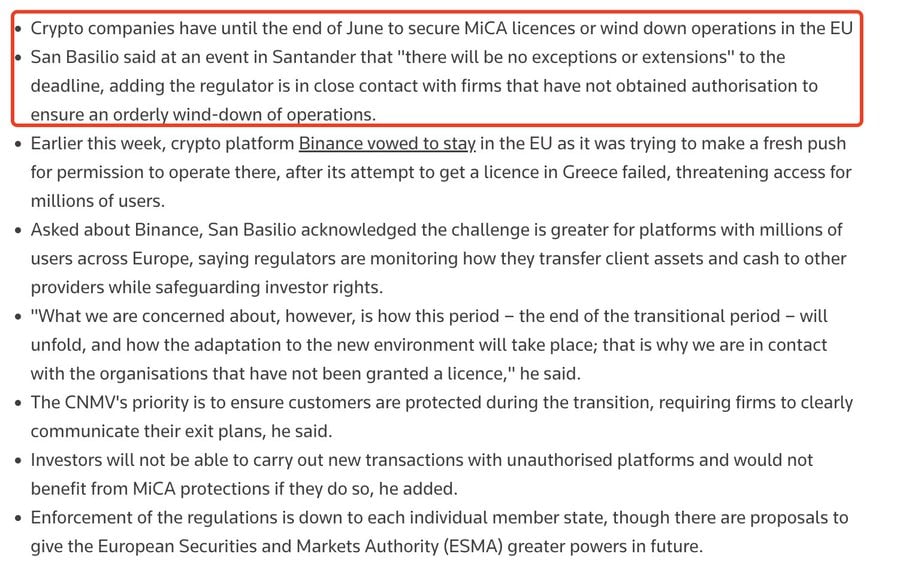
CNMV confirms: "No exceptions or extensions"

CNMV confirms: “No exceptions or extensions”. Source: Reuters

This means users still need to monitor direct announcements from Binance, as the ability to continue trading, open new positions, use yield-generating products, or access advanced services may vary by country and account status. The scale of affected EU users has not yet been publicly confirmed by Binance.

Why MiCA Matters

MiCA, short for Markets in Crypto-Assets Regulation, is the EU’s common regulatory framework for crypto-assets and related services. The regulation is designed to replace fragmented country-by-country approaches with a more unified system across the bloc.

With a MiCA license, a crypto service provider can use a passporting mechanism to operate in multiple EU countries based on a license granted in a single member state. This is why the Greek application held great significance for Binance: if licensed, the exchange could use that license as a foundation to serve the wider EU market.

MiCA sets requirements for governance, capital, operational controls, user protection, information transparency, technology security, and market abuse prevention. For major exchanges like Binance, the licensing process also places a heavy focus on compliance capacity and the “fit and proper” standards of individuals with significant control or influence.

The compliance issue is a sensitive point in Binance’s track record. In 2023, Binance and Changpeng Zhao, commonly known as CZ, reached a settlement with the U.S. Department of Justice, in which the exchange pleaded guilty and agreed to pay a total of $4.316 billion to resolve allegations related to anti-money laundering violations, unlicensed money transmitting, and sanctions. CZ stepped down as CEO and pleaded guilty to failing to maintain an effective AML program.

In recent updates, Binance stated it now has over 1,500 personnel in compliance roles and has prevented nearly $7 billion in potential losses from fraud. CZ also reacted on X, stating that the EU is cutting users off from the world’s best liquidity pool and arguing that liquidity is a form of consumer protection. This view contrasts with MiCA’s approach, which prioritizes licensing, risk control, and investor protection within a unified legal framework.

What Comes Next

Binance said its commitment to Europe remains unchanged, and the exchange is confident it can secure a license in another EU member state in the coming months. However, Binance has not announced which country it will apply to or pursue.

During the period without a license, affected accounts will need to monitor emails and in-app notifications for specific options. Binance stated it will provide direct guidance if users need to take further steps.

The next points to watch are ESMA’s CASP register, public responses from the HCMC or other national regulators, and any announcements from Binance regarding its new target market for licensing. If granted a license in a member state, Binance can restore its path to serving the broader EU under the MiCA framework.

In the short term, this remains a major setback for Binance in Europe. The exchange insists it is not leaving the region, but missing the MiCA deadline pushes its EU operations into a restricted phase, while already-licensed platforms gain a clearer advantage in continuing to serve users under the new regulatory framework.


Source link

Leading Prop Firms Crypto Traders Use for Altcoins and Futures in 2026

0
Leading Prop Firms Crypto Traders Use for Altcoins and Futures in 2026


Most prop firm roundups treat crypto as a footnote: a handful of BTC and ETH contracts bolted onto a platform built for forex. That works until you trade the way active crypto desks actually trade, across dozens of altcoins and perpetual futures, at any hour of the day. Finding the leading prop firms crypto traders rely on for that style means looking past the headline profit split and checking what sits underneath it. Deep pair coverage, real exchange execution, and a rulebook that accounts for crypto volatility instead of punishing it.

This list ranks three firms on the criteria that decide outcomes for altcoin and futures work, not on general brand recognition. The backdrop is worth keeping in view: across more than 300,000 accounts tracked by FPFX Tech, roughly 14% of traders pass the challenge and only about 7% ever reach a payout. Against those odds, the firm you pick is not a branding decision. If your strategy lives in second and third tier tokens and perps, the right pick looks different from the usual top of the table.

What Altcoin and Futures Traders Actually Need

A generic firm ranking optimizes for the wrong things. For altcoin prop trading, the requirements get specific fast, and a firm either meets them or it does not.

Pair depth, at least 100 instruments. A desk that lists 30 majors cannot support a strategy built on rotating altcoin setups. If your edge is reading momentum in lower-cap tokens, a firm that only quotes the top ten has already priced you out before you place a trade. Coverage is the gate everything else passes through.

Real perpetual futures, not spot CFDs in disguise. Perps are how most crypto traders express leveraged and directional views, with funding rates and 24/7 settlement that spot products do not replicate. A crypto futures prop firm without genuine perpetual coverage is a spot shop with extra steps, and it will not behave the way your live strategy expects.

Leverage that matches the asset class. Crypto capped at 1:2 or 1:3 does not reflect how positions get sized in this market. Altcoin traders need room to size around volatility, not have the platform size against them by default.

24/7 access and weekend holds. Crypto never closes, so any firm that forces a Friday exit hands you a structural disadvantage every single week. Weekends are when some of the sharpest moves happen, and being locked out of them is a real cost, not a minor inconvenience.

Live exchange liquidity. Orders routed to a real order book on a venue like Bybit or Kraken give you genuine fills and spreads. Synthetic CFD feeds can print artificial wicks that stop you out at a price that never traded on any real venue. For scalpers and high-frequency strategies, that gap between simulated and live is the difference between a clean exit and a phantom stop.

Hold any firm against those five points and the field narrows quickly. The names that survive are the ones built for crypto, not retrofitted into it.

The Leading Prop Firms Crypto Traders Use for Altcoins and Futures, Ranked

The ranking below weighs three things in order: pair coverage, execution model, and futures support. Those are the criteria that actually separate a firm for this niche, and they are where a crypto-native specialist and a forex-first platform diverge most. Brand reputation and total payout volume matter, but they sit lower on the list when your entire book is altcoins and perps.

1. HyroTrader

HyroTrader is built only for crypto, and the numbers show it. Its Bybit integration gives traders real fills against live order books across more than 700 perpetual pairs. For regions where Bybit is restricted, including the United States and Canada, its support to CLEO platform runs on Binance market data and covers more than 500 pairs, with full API access for algorithmic strategies and adjustable leverage up to 1:100. Both routes support perpetual futures, and the product extends into spot and crypto options.

As a dedicated crypto prop trading firm, HyroTrader routes every order to live exchange execution rather than an internal price engine. For altcoin traders, that is the whole point. More than 500 pairs is an order of magnitude beyond the roughly 30 crypto CFD contracts you get at forex-first firms, so if your edge sits in lower-cap tokens, that coverage is what makes the strategy possible at all. As a crypto futures prop firm, it gives you perpetual contracts on the long tail of the market, not just the majors that every platform carries.

The profit split starts at 80% and scales in steps to a 90% ceiling as you build a funded track record, rising 5% roughly every four months and reaching the top tier after about 16 months of consistent trading. The starting figure is lower than some competitors advertise, but the 90% ceiling matches the industry standard, and it is reached on performance rather than a paid upgrade. Payouts settle in USDT or USDC, usually within 12 to 24 hours of approval, and the first withdrawal can be requested a single full day after the first funded trade. Evaluations have no time limit—only a minimum trading-day requirement—allowing traders to progress at their own pace without the pressure of a fixed deadline.

Beyond its core trading platform, the ecosystem offers features that set it apart from many competitors. Traders can compete in live tournaments for the chance to win six-figure funded accounts, receive one-on-one guidance through a mentorship program led by experienced crypto traders, and refine their strategies in CLEO’s free backtesting environment. For traders focused on altcoins, this combination of funding opportunities, education, and advanced trading tools provides a level of support that’s difficult to find elsewhere.

HyroTrader does come with a few limitations that prospective traders should consider. Its evaluation rules are more restrictive than those of many competitors, including a per-trade risk limit and a trailing daily drawdown by default. However, traders can opt for the paid Swing upgrade, which replaces the trailing drawdown with a static one for more predictable risk management. The platform also focuses exclusively on cryptocurrencies, meaning it doesn’t support forex, stocks, or commodities, and all payouts are made in stablecoins rather than via traditional bank transfers. For traders dedicated to crypto futures and altcoins, these conditions are unlikely to be a drawback. Those seeking exposure to multiple asset classes through a single prop firm, however, may find the platform less suitable.

2. FundedNext

FundedNext stands out by giving traders more flexibility than many competing prop firms. Launched in the United Arab Emirates in 2022, the company offers multiple evaluation models, a scaling program that can grow accounts into the millions, and one of the more appealing profit-sharing structures in the industry. Traders start with an 80% profit split, with the option to increase it to as much as 95% through a paid upgrade. Unlike most prop firms, FundedNext also rewards successful traders during the evaluation phase, offering a 15% profit share before they even receive a funded account. Its primary account types allow positions to remain open over the weekend, and the firm guarantees payouts within 24 hours, making it one of the faster and more flexible options available for active traders.

The catch for crypto traders is the foundation. The firm added crypto to its lineup, but the architecture stays forex-first and the execution simulated. Crypto trades as CFDs on the familiar names, BTC, ETH, XRP, DOGE, and a modest list beyond them, inside a broader basket of around 78 assets. Crypto leverage sits below what a crypto-native firm offers, and the top 95% split is an upgrade rather than a standard, so the real comparison is against a competitor’s base number, not the headline. For altcoin prop trading specifically, the tradable list runs thin next to a platform routing orders to live exchange order books. The flexibility is real and worth weighing. The crypto depth is not the reason to choose it.

3. FTMO

FTMO is the most established name in the broader prop industry, and the reputation is earned. Founded in Prague in 2015, it reports more than $500 million in cumulative payouts and serves traders in over 140 countries. Its December 2025 acquisition of OANDA added regulated brokerage licenses across eight jurisdictions, including a compliant route for United States traders, which is a level of regulatory grounding almost no crypto-native firm can claim. The platform is polished, the rules are transparent, and the multi-asset breadth is genuine.

For crypto-focused traders, the platform’s limitations are built into its design rather than being minor drawbacks. Leverage is relatively conservative, capped at around 1:3 for crypto CFDs and reduced to 1:1 on Swing accounts that allow weekend holding. Standard accounts require all positions to be closed before the weekend, despite cryptocurrency markets operating around the clock. The crypto offering is also limited to roughly 32 CFD pairs, with trades executed in a simulated environment instead of being routed to live exchanges. None of these factors diminish FTMO’s reputation as a leading proprietary trading firm. Instead, they reflect its primary focus on forex and traditional markets, with cryptocurrency serving as an additional asset class rather than the platform’s core specialty. Traders who value access to multiple markets may appreciate that balance, but those concentrating exclusively on altcoins and crypto futures will likely find the crypto-specific features less comprehensive than those offered by dedicated crypto prop firms.

Feature Comparison

FeatureHyroTraderFundedNextFTMOCrypto pair count700+ on Bybit, 500+ on CLEOModest crypto list within ~78 assets~32 crypto CFD pairsMax crypto leverageUp to 1:100Below crypto-native levels~1:3, 1:1 on SwingPlatformsBybit, CLEO (Binance data)MT4, MT5, cTraderMT4, MT5, cTraderProfit split80% scaling to 90%80% base, up to 95% (paid add-on)Up to 90%Payout methodUSDT/USDC, 12 to 24 hoursCrypto, wire, and othersBank or wireEvaluation type1-step or 2-step, no time limitMultiple paths, no time limit2-step evaluationAltcoin and futures fitLive exchange execution, perps and optionsSimulated CFDs, limited depthSimulated CFDs, weekend close

The Bottom Line

For altcoin and futures traders specifically, crypto-native infrastructure matters more than general reputation. Among the leading prop firms crypto traders can choose from in 2026, HyroTrader fits this niche, not because it wins some vague overall title, but because of pair depth, live exchange execution, and real perpetual coverage that a forex-first crypto futures prop firm cannot match. The 90% scaling ceiling and same-day stablecoin payouts hold up as a competitive standard for anyone whose strategy lives entirely in digital assets.

FundedNext is the call if you value evaluation flexibility and want some multi-asset room, with the honest caveat that its crypto list is shallow and its execution simulated. FTMO makes sense if you want one polished, well-regulated account across many markets and you accept the lower crypto leverage and weekend limits as the cost of that breadth. The model is largely unregulated and most funded accounts remain simulated, so the sensible approach holds regardless of which name you pick: verify the operating history, read the rulebook before the split, start small, and scale only after a first clean withdrawal. Choose the prop firm that aligns with your trading style, verify the latest rules and pricing on the firm’s official website before making a purchase, and the right choice will usually become clear.


Source link

Bank of England Replaces Proposed Stablecoin Holding Caps With £40B Issuance Guardrail

0
Bank of England Replaces Proposed Stablecoin Holding Caps With £40B Issuance Guardrail


On June 22, the Bank of England (BoE) announced a policy and draft rules shifting from proposed limits on individual and corporate stablecoin holdings to a temporary issuance ceiling of £40 billion for each systemic stablecoin product in the UK. This change applies to stablecoins recognized as systemic by HM Treasury, aiming to make GBP-denominated payment products easier to operate while still limiting the risk of deposits leaving the banking system.

What Changes Under the Draft Rules

In its 2025 proposal, the BoE had considered imposing holding limits of £20,000 for individuals and £10 million for corporates. These limits never came into effect and will not be pursued further under the newly published policy statement and draft Code of Practice.

Accordingly, each systemic stablecoin product will be subject to an initial maximum issuance limit of £40 billion. This limit is calculated on the total circulating token supply of each individual product, not the overall market size, nor is it a blanket cap applied across an issuer with multiple stablecoins.

Under the draft rules, individuals and corporations will not face limits on the size, frequency, or type of stablecoin transactions, aside from constraints imposed by anti-money laundering, sanctions, and other existing laws. This mechanism eliminates the requirement to track real-time balance limits for individual users, which was one of the operational issues raised in consultation responses.

Why BoE Changed Course

The BoE stated that it dropped the proposed holding caps after consultation feedback raised concerns that the mechanism was complex, costly, and difficult to justify if only implemented during a transitional phase.

The central bank maintains its core concern regarding the rapid shift of bank deposits into stablecoins, which could impact bank liquidity and the capacity to extend credit to the economy. Therefore, the BoE shifted to capping the total issuance for each systemic stablecoin instead of monitoring the balances of individual consumers and corporates.

To set the £40 billion level, the BoE modeled a stress scenario, monitoring how many banks could fall below the 100% Liquidity Coverage Ratio threshold, the demand for central bank liquidity borrowing, and the likelihood of banks having to sell assets. The BoE stated that this ceiling provides a level of protection for credit supply equivalent to the old holding caps, but is easier to implement.

How the Draft Framework Works

The draft framework still requires systemic stablecoins to be backed 1:1. Under normal operating conditions, an issuer can hold a maximum of 70% of backing assets in short-term UK government debt securities with a remaining maturity of no more than six months; a minimum of 30% must be held as deposits at the BoE, and this portion will not earn interest. The BoE stated that this requirement reflects the design of stablecoins as a means of payment rather than a savings or investment product. For a stablecoin issued at the £40 billion limit, the 70/30 structure corresponds to a maximum of £28 billion in UK government debt securities and a minimum of £12 billion in deposits at the BoE.

Issuers must process redemption requests in real-time where possible, or complete them within 24 hours after receiving a fully valid request, completing AML/KYC checks, and receiving the tokens from the person requesting the exchange. Issuers are also prohibited from paying interest based on the duration a holder owns the stablecoin, though rewards tied to payment activities may still be permitted.

The BoE expects systemic issuers to directly access payment systems to support redemptions and interoperability with other forms of money. The central bank also plans to establish a Central Bank Liquidity Facility, allowing eligible issuers to borrow deposits from the BoE by pledging UK government debt securities as collateral; operational details will be published in 2027.

What the £40 Billion Cap Means

The £40 billion limit caps the volume of stablecoins issued and circulating, rather than the volume of payments users can make within a day. The BoE stated that this level is set at a scale sufficient for issuers to maintain a viable business model and serve major payment use cases; according to the authority, a stablecoin at that level could support daily transactions equivalent to major UK payment systems, where Faster Payments and card schemes process an average of around £1.4–£2.2 billion per day. The £40 billion level is also equivalent to approximately 10% of the average value processed daily by CHAPS.

This cap still creates a trade-off if demand grows faster than the volume of tokens an issuer is permitted to launch, as the price of the stablecoin on the secondary market could rise above par value. The BoE believes that such a scenario would require large and sustained capital flows, while committing to review the ceiling regularly and relax or remove it once risks to the credit supply are mitigated.

What Happens Next

Issuers of qualifying stablecoins will initially be subject to supervision by the FCA, the regulator responsible for issuance, custody, and admission to trading in the UK. Once a stablecoin is recognized as systemic by HM Treasury, the issuer will transition to a co-supervisory model, where the BoE takes charge of prudential risk and financial stability, while the FCA continues to oversee conduct and user protection.

The BoE said it will soon publish a joint document with the FCA regarding how firms transition between these two regimes. The draft Code of Practice is currently open for consultation until September 22, 2026, while the final rulebook is expected to be finalized by the end of the year.

Parallel to that process, the FCA has selected Monee Financial Technologies, ReStabilise, Revolut, and VVTX for the stablecoin sandbox. The trials include payments, wholesale settlement, and crypto trading, with results expected to contribute to shaping the final stablecoin rules in 2026.


Source link

Aave Founder Kulechov Dismisses Rumors of Selling AAVE at a 70% Discount, Teases Aavenomics 3.0 – NFT Plazas

0
Aave Founder Kulechov Dismisses Rumors of Selling AAVE at a 70% Discount, Teases Aavenomics 3.0 – NFT Plazas


Stani Kulechov, founder of Aave — the largest decentralized lending protocol on Ethereum — has publicly dismissed reports that Aave Labs is in talks to sell a significant AAVE token allocation to Kraken’s parent company Payward at a steep discount to market value. While stopping short of denying that strategic partnership discussions are underway, Kulechov pushed back forcefully against the deal’s reported framing, using the controversy to restate Aave’s revenue model and announce a coming upgrade to its token economics.

The Report That Triggered the Pushback

CoinDesk reported on Thursday, citing two unnamed sources, that Kraken parent firm Payward is in talks to buy a 15% stake in the Aave protocol at a $385 million valuation — a figure that would represent just 30% of the AAVE token’s fully diluted valuation. A separate report elaborated that the proposed transaction was valued at approximately $71 million and involved Kraken investing 35,000 ETH in exchange for 250,000 AAVE tokens and a 15% equity stake in Aave Group.

The implied discount to AAVE’s market price drew immediate community backlash — and a swift rebuttal from the top.

“First off, there is NO WAY we’d sell AAVE at a 70% discount lol,” Kulechov wrote in an X post on Thursday, calling the article’s framing inaccurate.

Kulechov said Aave Labs owns an allocation of AAVE that multiple market participants have discussed purchasing, either directly or indirectly, through deeper long-term partnerships — but separated those discussions from the idea that Aave would sell tokens cheaply against token-holder interests.

Aave founder Stani Kulechov dismisses rumors of selling $AAVE at a 70% discount

Aave founder Stani Kulechov dismisses rumors of selling $AAVE at a 70% discount

Revenue Model Clarified

The controversy gave Kulechov a platform to reinforce Aave’s restructured economics. Under the Aave Will Win (AWW) proposal, already passed by the DAO, 100% of Aave Protocol and GHO revenue is directed to the AAVE token. The framework covers all product revenue streams, including the Aave App, Aave Pro, and Swaps, with none of it flowing to Aave Labs, which operates solely as a service provider to the DAO.

The AWW proposal passed with about 75% support in April 2026, redirecting 100% of protocol and Aave-branded product revenue to the DAO and AAVE token holders, with the DAO approving multi-year funding for Labs in return.

Kulechov confirmed that all intellectual property — including the Aave brand and any software built for Aave — belongs to AAVE token holders, not Aave Labs, under the current governance structure. He added that the protocol is currently generating $134 million in annualized revenue, all directed to the Aave DAO.

Aavenomics 3.0 and Automated Buybacks

Beyond clarifying the revenue model, Kulechov teased a significant upgrade to the protocol’s token mechanics. He revealed that the Aave team is designing Aavenomics 3.0, which includes a new automated and non-discretionary AAVE buyback mechanism, with further details to follow.

The planned upgrade extends a discretionary buyback program already cleared to purchase up to $50 million of AAVE per year. An automated system would reduce reliance on governance votes for individual buyback decisions, creating a more predictable and continuous link between protocol revenue and token purchases — a structure likely to appeal to institutional participants evaluating AAVE as a yield-bearing asset.

Context: The KelpDAO Fallout

The Kraken reports surface against a difficult backdrop. After the April 18 KelpDAO exploit, an attacker deposited $292 million in stolen rsETH into Aave V3 as collateral and borrowed substantial amounts of wrapped ETH against it, saddling the protocol with an estimated $196 million in bad debt. Aave’s total value locked collapsed from $26.4 billion to nearly $20 billion within days. Kulechov confirmed at the time that Aave’s own smart contracts were not compromised.

The incident weighed heavily on user confidence, with Aave’s TVL dropping roughly $12 billion — about 46% of its deposits — in just days after the attack. Deposits currently sit near $12 billion. Earlier this month, Aave released an updated risk framework to prevent situations like the KelpDAO attack.

AAVE’s TVL Data (Source: DefiLlama)AAVE’s TVL Data (Source: DefiLlama)

AAVE’s TVL Data (Source: DefiLlama)

Kraken’s Broader Strategy

For Kraken, a stake in Aave would fit a pattern of aggressive expansion ahead of its anticipated public listing. The exchange agreed this year to buy derivatives venue Bitnomial for up to $550 million, securing rare US derivatives licenses. The two companies already have an established relationship: Kraken’s Layer 2 Ink launched a white-label instance of Aave called Tydro last year to serve as its core lending infrastructure, following a 99.8% DAO vote to license Aave’s code to the network.

Market Reaction and Analyst Outlook

Despite the post-KelpDAO turbulence, AAVE has attracted bullish institutional attention. Following Kulechov’s post, the token reached an intraday high of $87.50 before easing to around $82, while continuing to receive support from Standard Chartered’s previously published $3,500 price target for AAVE by end of 2030. Grayscale Research has separately flagged AAVE as undervalued at current prices under a cash-flow model applying traditional fintech earnings multiples.

Kulechov closed with a pointed statement on alignment: “Everyone at Aave Labs and Aave DAO works for $AAVE.” A quarterly community call is expected within weeks, where the Kraken partnership status and Aavenomics 3.0 details are anticipated to become clearer.


Source link

Ripple’s RLUSD Launches as Japan’s First Regulated Foreign Stablecoin – NFT Plazas

0
Ripple’s RLUSD Launches as Japan’s First Regulated Foreign Stablecoin – NFT Plazas


Ripple has officially launched its dollar-backed stablecoin Ripple USD (RLUSD) in Japan, marking a significant milestone for both the company and the country’s evolving digital asset landscape. The rollout, conducted in partnership with SBI Holdings and its subsidiary SBI VC Trade, makes RLUSD the first foreign-issued stablecoin to receive regulatory approval under Japan’s updated payment framework — a development that could reshape how Japanese institutions and retail users access dollar-denominated liquidity on-chain.

Regulatory Approval Opens the Door

The launch follows formal approval from Japan’s Financial Services Agency (JFSA), which cleared RLUSD for distribution under a revamped stablecoin framework that took effect on June 1, 2025. Under Japan’s Payment Services Act, RLUSD is categorized as a new type of electronic payment instrument — a classification specifically designed to accommodate foreign-issued stablecoins that meet Japan’s safety and compliance thresholds.

The regulatory clearance is notable. Japan has historically maintained one of the world’s more cautious approaches to digital asset oversight, and obtaining JFSA approval signals that RLUSD satisfies the operational and reserve standards Japanese regulators demand. For Ripple, it represents entry into one of Asia’s most mature and strategically important financial markets.

“Japan has long been a leader in digital asset adoption, underpinned by both regulatory clarity and financial innovation,” said Jack McDonald, Ripple’s Senior Vice President of Stablecoins, in the official announcement. “This launch marks an important step in expanding access to transparent, regulated USD-backed stablecoins like RLUSD for financial institutions, consumers, and businesses in Japan.”

Ripple USD ($RLUSD) is now officially available in Japan

Ripple USD ($RLUSD) is now officially available in Japan

SBI Partnership: A Decade in the Making

The distribution vehicle for RLUSD in Japan is SBI VC Trade’s VCTRADE platform, which serves both institutional and retail customers. RLUSD is now live and accessible to all eligible users on the platform.

The partnership between Ripple and SBI Group is not new. The two companies have collaborated since 2016 on blockchain-based financial infrastructure across Japan and the Asia-Pacific region, making this launch the latest — and perhaps most consequential — chapter in a relationship spanning nearly a decade. The specific RLUSD rollout was formalized through a memorandum of understanding signed in August 2025, which laid the groundwork for the regulatory approval process and commercial launch that followed.

SBI VC Trade CEO Tomohiko Kondo described the moment as a major milestone: “Ripple and the SBI Group have worked closely together for many years with a shared vision of advancing the future of on-chain finance. The introduction of RLUSD represents a major milestone in our ongoing collaboration and our efforts to drive innovation in digital finance.”

SBI’s broader commitment to the XRP ecosystem has also accelerated in parallel. The firm has expanded XRP access across Japan’s retail market, and separately, XRP secured a spot listing on Rakuten Wallet earlier this year — underscoring growing institutional support for Ripple-affiliated digital assets in the country.

Use Cases: Payments, Tokenization, Collateral

Ripple is positioning RLUSD in Japan as a functional financial instrument rather than a speculative asset. McDonald outlined three primary use cases: cross-border payments, asset tokenization, and collateral management. Each speaks directly to pain points in Japan’s traditional financial system, where settlement times and cross-currency friction remain persistent inefficiencies.

For payments, RLUSD offers faster settlement finality compared to conventional wire infrastructure. On the tokenization front, the stablecoin can serve as a settlement layer for tokenized real-world assets — an area attracting growing institutional interest globally. As collateral, RLUSD provides a regulated, dollar-backed instrument that financial counterparties can hold or post without the volatility exposure associated with native crypto assets.

Ripple has also flagged programmable trade settlements and supply chain finance as next-generation applications being actively explored, pointing to an ambition that extends well beyond retail payments.

Market Cap Context

RLUSD’s arrival in Japan comes after a period of rapid growth for the stablecoin since its late 2024 launch. RLUSD’s market cap reached an all-time high of approximately $1.8 billion in early June 2026 before pulling back to around $1.59 billion. Despite that recent cooling, the figure still represents roughly 271% growth over the prior year — a trajectory that reflects accelerating institutional demand for a regulated, enterprise-grade alternative to incumbents like USDC and USDT.

What Comes Next

Japan is a meaningful beachhead, but Ripple has made clear that RLUSD’s expansion is ongoing. The stablecoin is already deployed across multiple markets to enable cross-border liquidity and faster settlements.

The more immediate question is whether RLUSD can capture meaningful market share in Japan itself, where USDC and USDT currently dominate stablecoin usage among exchanges and institutional desks. The combination of JFSA approval, an established distribution partner in SBI, and a clear institutional use-case roadmap gives Ripple a credible foundation. Whether that translates to adoption at scale will become clearer in the months ahead.


Source link

Chainlink Taps 50+ Banks Across Two Continents for Real-Time Stablecoin FX Settlement Test – NFT Plazas

0
Chainlink Taps 50+ Banks Across Two Continents for Real-Time Stablecoin FX Settlement Test – NFT Plazas


Project Pangea brings together Korean and European banking coalitions to tackle the $9.6 trillion-a-day foreign exchange market’s persistent settlement delays using onchain infrastructure.

Chainlink has launched Project Pangea, a cross-border foreign exchange settlement initiative involving more than 50 financial institutions representing over $10 trillion in assets under management. The project aims to replace the industry’s standard two-business-day settlement cycle with instant, atomic transactions powered by regulated stablecoins and blockchain infrastructure — without requiring banks to abandon their existing systems.

A Coalition Built for Scale

The initiative brings together four core organizations: Chainlink, FairSquareLab, UniKA (Unified Korea Alliance), and Qivalis. On the Korean side, UniKA represents more than 10 commercial banks, including Shinhan Bank, JB Bank, and Kbank. Qivalis rounds out the European contingent, representing a consortium of 37 banks across the continent.

The breadth of institutional participation sets Project Pangea apart from previous blockchain proof-of-concept exercises. Niki Ariyasinghe, Chainlink’s vice president of Asia-Pacific and the Middle East, was direct about the project’s ambitions: “This is not just a POC. Everyone’s coming in with their eyes wide open.”

Chainlink taps 50+ banks for stablecoin settlement test

Chainlink taps 50+ banks for stablecoin settlement test

The Problem Project Pangea Is Solving

The global FX market processes more than $9.6 trillion in daily volume, yet cross-border transactions remain trapped in legacy infrastructure that can take 48 hours to settle. During that window, capital is effectively frozen — unavailable to either party for other purposes and exposed to counterparty and currency risk.

“If I’m sending money to you and it’s lost in transit for quite some time, you don’t receive it, and that money isn’t able to be used,” Ariyasinghe explained. “To reduce that time as much as possible, for customers to access that money absolutely as fast as possible, has to be a good thing.”

Project Pangea specifically targets this problem through atomic Payment-versus-Payment (PvP) swaps using compliant euro and South Korean won stablecoins. In a PvP model, both legs of a currency trade settle simultaneously — or not at all — eliminating the settlement risk that arises when one party delivers funds before the other.

How the Architecture Works

Rather than asking banks to overhaul their core systems or acquire cryptocurrency, Project Pangea layers blockchain infrastructure on top of existing rails. The architecture is divided into three distinct layers.

The banking layer operates through familiar ISO 20022 messaging standards and Swift infrastructure, meaning participating institutions send instructions through the same systems they already use. The connectivity layer is handled by Chainlink’s suite of institutional tools: the Cross-Chain Interoperability Protocol (CCIP) for moving stablecoins between networks, Chainlink Data Streams for real-time FX market pricing, and the Chainlink Runtime Environment (CRE) to bridge traditional banking systems with blockchain networks. The settlement layer executes trades through FairSquareLab’s onchain FX technology and the dedicated Pangea L1 blockchain, with smart contracts also deployable on Ethereum and Polygon.

FX swaps execute at oracle-based market rates, with built-in mechanisms to maintain liquidity and minimize slippage. Chainlink has noted that enterprise revenue and service fees generated through the project will be converted into LINK tokens and held in the Chainlink Reserve.

The Chainlink Reserve stores the strategic reserve of LINK funded by revenue.The Chainlink Reserve stores the strategic reserve of LINK funded by revenue.

The Chainlink Reserve stores the strategic reserve of LINK funded by revenue.

Fitting Into a Broader Institutional Shift

Project Pangea arrives as stablecoin-based settlement is gaining serious traction across the global banking sector. SWIFT has independently explored blockchain-based payment systems as stablecoins grow in scale, and the Bank for International Settlements recently concluded tokenization trials demonstrating atomic settlement across seven central banks and more than 40 financial institutions.

For Chainlink specifically, this project extends a significant institutional infrastructure push. The company’s CCIP stack recently surpassed $110 billion in total value secured across cross-chain tokens and DeFi data feeds — a milestone that has helped position it as a credible enterprise-grade connectivity layer for traditional finance.

The project also expands Chainlink’s footprint in the Korean won stablecoin ecosystem. Separately, the company recently enabled KRWQ — a KRW-backed stablecoin developed by IQ and Frax Finance — to become the first Korean won stablecoin with automated, real-time reserve verification through Chainlink Proof of Reserve and Data Streams. That integration replaces delayed manual auditing with continuous, onchain proof of backing, reducing counterparty risk in DeFi applications.

What Comes Next

Project Pangea is structured with a steering committee of five core entities alongside multiple participating commercial banks. The immediate goal is to test and develop direct atomic swaps between compliant fiat-referenced digital assets. Whether the model can meet compliance, risk, and liquidity standards at institutional scale remains the central question.

As of publication, Chainlink’s LINK token was trading at $7.59, down 3.2% over 24 hours, with a 24-hour trading volume of approximately $246 million and a market capitalization near $5.68 billion.

The long-term success of Project Pangea will hinge on several variables: technical performance under real-world load, regulatory clarity in both European and Korean jurisdictions, cost efficiency relative to existing settlement infrastructure, and the willingness of participating institutions to move from pilot participation to live deployment. If those conditions align, the project could mark a meaningful step toward making real-time FX settlement the rule rather than the exception.


Source link

MoneyGram Joins Solana as Validator in Broader Stablecoin Strategy

0
MoneyGram Joins Solana as Validator in Broader Stablecoin Strategy


On June 22, 2026, MoneyGram announced it had become an active validator on the Solana network and joined the Solana Developer Platform (SDP), pushing the cross-border money transfer company deeper into blockchain infrastructure for payments. MoneyGram stated this is part of its strategy to build open and interoperable stablecoin infrastructures.

However, the announcement did not specify any new remittance services on Solana, deployment corridors, the stablecoins to be used, launch timelines, or user fees.

From User to Operator

Most users know MoneyGram as an international money sending and receiving service. Operating a validator places MoneyGram in a different role: participating in Solana’s infrastructure layer, where payment applications and financial services can be built.

In its June 22 press release, MoneyGram stated that the company is staking SOL, processing blocks, and supporting network security. On Solana, validators validate transactions and help operate the network under a proof-of-stake mechanism. The influence of a validator in this mechanism depends on the amount of SOL staked. MoneyGram’s announcement did not disclose the validator address or the scale of the SOL stake, so the impact of this node within the validator set cannot be independently assessed.

Luke Tuttle, Chief Product and Technology Officer at MoneyGram, also stated that the company will stake SOL, process blocks, and support network security at the protocol level. This marks a shift from integrating blockchain technology into payment operations to directly participating in operating a part of a public blockchain infrastructure.

Why Solana

Along with its validator role, MoneyGram has joined the SDP, an API platform aimed at institutions looking to issue digital assets, integrate payments, and build financial products on Solana. According to the Solana Foundation, the SDP is designed to help enterprises build and deploy financial services on the blockchain with the right tools for operational and compliance needs.

Prior to MoneyGram, Mastercard, Western Union, and Worldpay joined the SDP from an early stage, showing that Solana is positioning the SDP as a tool for financial and payment institutions to build on-chain products. With over 60 million active customers globally and nearly 500,000 retail agent locations, according to MoneyGram, the company can bring large-scale remittance operational experience to the SDP when developing subsequent products.

Remittance Economics

The global average cost of sending money remained at 6.36% in the third quarter of 2025, according to the World Bank’s Remittance Prices Worldwide report. The fees customers pay come not only from transaction settlement but are also influenced by foreign exchange spreads, compliance checks, liquidity, and cash payout networks in the receiving country.

In this context, MoneyGram operating a Solana validator does not in itself reduce money transfer fees. Validators support transaction validation and network operations, but do not determine the price of a remittance transaction, the applicable exchange rates, or how customers receive money in each market.

The potential value lies in the back-end operations of customer transactions. If MoneyGram uses stablecoins to settle with partners faster or manage liquidity more efficiently, the company could improve operational costs and capital efficiency. But these benefits do not automatically translate into lower fees for senders.

A Multi-Chain Strategy

Solana is not the only blockchain in MoneyGram’s stablecoin strategy. On June 2, the company launched MGUSD, a USD stablecoin issued natively on Stellar. In its Solana announcement, MoneyGram also stated that blockchain and stablecoins have been integrated into the company’s treasury operations, product development, and payments for years.

The fact that MGUSD is issued on Stellar while MoneyGram operates a validator and participates in the SDP on Solana shows that the company is building a presence across multiple blockchains. However, MoneyGram has not said that MGUSD will be issued on Solana, nor has it announced how use cases will be split between the two networks. At this stage, Stellar remains the issuance network for MGUSD, while Solana is where MoneyGram is expanding its role at the infrastructure and product development layer.

What Comes Next

The June 22 announcement places MoneyGram into Solana’s operational layer but does not yet create a new remittance option for customers. The company has not indicated whether Solana will be used for which stablecoin, which market, or which step in the money sending and receiving process.

Only when those details emerge can it be assessed whether the validator role and SDP participation are just an infrastructure-building step or will become a part of MoneyGram’s payment network at a commercial scale.


Source link

ICE and OKX Form Joint Venture to Bridge Wall Street and Blockchain in Historic Tokenized Markets Deal – NFT Plazas

0
ICE and OKX Form Joint Venture to Bridge Wall Street and Blockchain in Historic Tokenized Markets Deal – NFT Plazas


Intercontinental Exchange (ICE), the Fortune 500 company that owns the New York Stock Exchange, and OKX, one of the world’s largest cryptocurrency exchanges, have announced the formation of a landmark 50-50 joint venture aimed at building next-generation infrastructure for tokenized and digitally native financial products. The venture, to be called OKXICE, will be co-chaired by former New York Governor Andrew Cuomo and ICE Senior Vice President of Futures Markets Trabue Bland. The announcement, made on June 22, 2026, marks one of the most significant convergences of traditional finance and blockchain technology to date.

A New Architecture for Global Markets

The joint venture, subject to regulatory approvals, will operate as a U.S.-registered broker-dealer and futures commission merchant (FCM), with its primary function being to give OKX’s 120 million customers access to ICE futures markets and NYSE tokenized equities. In plain terms, the deal is designed to bring the full weight of Wall Street’s most trusted infrastructure into crypto-native trading environments — at a scale the industry has not seen before.

For crypto traders accustomed to digital assets, the appeal is obvious. Tokenized equities could offer fractional ownership, near-instant settlement, and broader market access without leaving the platform they already use. Former Governor Cuomo put it more vividly: “You can virtually walk through the front door of the New York Stock Exchange through your smartphone, and you can do that seven days a week in a way you never could before.”

Beyond the core broker-dealer and FCM structure, the joint venture will explore what the announcement describes as “adjacent opportunities for regulatory-compliant blockchain-enabled markets” — language that leaves the door open for tokenized bonds, commodities, and other asset classes to follow equities onto the shared infrastructure.

ICE and OKX Launch Joint Venture for Tokenized Markets

ICE and OKX Launch Joint Venture for Tokenized Markets

The Relationship’s Origins

Monday’s announcement did not emerge out of thin air. The groundwork was laid on March 5, 2026, when ICE announced an approximately $200 million minority investment in OKX at a valuation of roughly $25 billion, a deal that came with a board seat for ICE and a framework for commercial collaboration, particularly around tokenized equities distributed through OKX’s platform.

Earlier in May 2026, OKX launched perpetual futures linked to ICE’s Brent and WTI crude oil benchmarks, offering an early glimpse of how the relationship could evolve. Oil futures products are already in active development at the new venture, with securing the FCM license and broker-dealer registration topping the near-term priority list.

The arrangement also runs in both directions. ICE plans to license OKX’s spot price data for use in its U.S.-regulated futures products. This bidirectional data and market access agreement underscores the depth of integration the two companies are pursuing.

High-Profile Leadership

Few elements of this deal have drawn more attention than the appointment of former New York Governor Andrew Cuomo as co-chair. Cuomo, who also served as New York State Attorney General and U.S. Secretary of Housing and Urban Development, began working with OKX in 2023 and is expected to spend the majority of his time overseeing the joint venture’s operations.

Cuomo has framed the venture in broad societal terms. “The next chapter of financial markets will be defined by how well innovation and government regulation can move forward together,” he said. “I am personally excited by the prospect of the societal impact that blockchain technology can lead to: the democratization of finance, bringing basic financial services to underserved populations.”

Trabue Bland echoed the ambition from ICE’s side. “ICE’s global benchmarks and regulated market technology have earned the trust of institutions and traders everywhere and now, through our partnership with OKX, we are working towards extending that reach to OKX’s 120 million retail traders,” he said.

Regulatory Footprint and Compliance

Regulatory credibility is central to the venture’s value proposition. OKX holds licenses across the U.S., UAE, European Economic Area, Singapore, and Australia, giving the joint venture a regulatory footprint that most crypto-native firms lack. ICE, meanwhile, operates some of the most critical clearing and settlement infrastructure in global finance, including ICE Clear Credit and ICE Clear Europe.

That said, OKX’s U.S. history carries weight. A federal investigation into OKX was settled in 2025 for more than $500 million, with the underlying company admitting guilt to charges that it had operated illegally in the U.S. market. The exchange subsequently relaunched its U.S. operations. The joint venture structure, operating under ICE’s regulated umbrella, appears to be a deliberate effort to ground OKX’s expanded U.S. ambitions firmly within the compliance framework regulators demand.

Operating as a U.S.-based broker-dealer and futures commission merchant, the venture is expected to comply with strict financial oversight requirements — a regulatory foundation seen as essential for attracting institutional investors, many of whom have been cautious about entering digital asset markets due to concerns around compliance, custody, and market integrity.

ICE’s Broader Digital Asset Push

The initiative extends ICE’s broader push into digital assets, which includes backing Bakkt and a multibillion-dollar investment in prediction market Polymarket. The OKXICE joint venture is the most operationally ambitious move yet in that strategy, positioning ICE not merely as a financial backer of crypto firms but as an active builder of blockchain-enabled market infrastructure.

Both companies have also outlined plans for broader work on clearing, risk management, and multi-chain custody — signaling that the venture’s scope extends well beyond a simple trading access agreement.

What Comes Next

The planned product rollout is targeted for the second half of 2026, pending regulatory approvals. Until broker-dealer and FCM registrations are secured, the venture remains a future roadmap rather than a live product. Both companies appear committed, however, to executing what could become the defining institutional framework for how tokenized financial products are built, regulated, and distributed globally.


Source link

Satoshi’s Lost-Coin Quote Turns 16, Reigniting Bitcoin Scarcity Debate – NFT Plazas

0
Satoshi’s Lost-Coin Quote Turns 16, Reigniting Bitcoin Scarcity Debate – NFT Plazas


Sixteen years after Bitcoin’s pseudonymous creator offered what may be the protocol’s most enduring philosophical aside, the crypto community is revisiting its implications with new data and renewed urgency.

The discussion happened on June 21, 2010, in a Bitcointalk thread called “Dying bitcoins.” A user had asked whether forgotten wallets meant the network would shrink over time. After replies from early contributors Laszlo Hanyecz and Gavin Andresen, Satoshi Nakamoto responded with a line that continues to circulate today: “Lost coins only make everyone else’s coins worth slightly more. Think of it as a donation to everyone.”

The quote was not a price prediction. It was an observation about scarcity — and one that has aged into a live economic question. With estimates suggesting millions of BTC may be permanently inaccessible, researchers and analysts are now asking how much of Bitcoin’s nominal 21-million-coin supply actually remains in circulation.

The Numbers Behind the Debate

Multiple reports put the midpoint estimate of permanently lost bitcoin at around 3.1 million BTC, with a central range of 2.7 million to 3.9 million BTC and a wider envelope spanning 2.3 million to 5.25 million BTC. Measured against a circulating supply of 20,045,680.42 BTC tracked by Glassnode as of June 20, 2026, that midpoint represents roughly 15.5% of all mined bitcoin.

That figure comes with a significant caveat: it cannot be proven with certainty. The blockchain can confirm that certain coins are unspendable, but it cannot confirm whether an unmoved coin is lost rather than simply being held.

Satoshi's Lost-Coin Quote Hits 16-Year Mark

Satoshi’s Lost-Coin Quote Hits 16-Year Mark

What the Data Actually Proves

The gap between the headline loss estimate and what can be verified on-chain is stark. A 2025 study by researchers Mohamed El Khatib and Arnaud Legout used entropy filtering and machine learning to identify confirmed burn addresses. Their model scanned over 1.28 billion addresses and determined that just 3,197.61 BTC had been permanently destroyed through block 840,682 in April 2024 — representing only 0.016% of total supply. Adding Bitcoin’s unspendable 50 BTC genesis block reward, the provable floor barely moves. Everything above that threshold relies on probabilistic modeling, not on-chain proof.

Dormancy Data and the Patoshi Question

Glassnode’s supply-by-age data for June 20, 2026, shows 3.557 million BTC untouched for more than 10 years, 1.690 million BTC in the 7-to-10-year band, and 1.479 million BTC in the 5-to-7-year range — placing roughly 5.25 million BTC dormant for over seven years. Glassnode classifies coins inactive beyond seven years as “Inert Supply,” treating them as likely lost, though old coins do occasionally move.

Complicating the picture further is the question of Bitcoin’s earliest mining activity. Sergio Demian Lerner‘s research identified a single dominant early miner — the so-called “Patoshi” pattern — responsible for roughly 1.1 million BTC. BitMEX Research later revised that figure down to 700,000 to 750,000 BTC, while Whale Alert pushed it higher to approximately 1,125,150 BTC across the first 54,316 blocks. Whether analysts treat those coins as lost, dormant, or unattributed swings the overall loss estimate by hundreds of thousands of BTC. Most attribute the Patoshi stash to Satoshi Nakamoto, though the coins have never moved and that attribution remains unproven.

The Patoshi Factor (Source: Bitcoin.com News)The Patoshi Factor (Source: Bitcoin.com News)

The Patoshi Factor (Source: Bitcoin.com News)

How Bitcoin Gets Lost

The mechanisms behind coin loss are varied. River’s 2025 Bitcoin custody report conservatively estimates that 1.57 million BTC have been permanently lost through self-custody failures, with 98% of those losses occurring before 2020. Loss typically occurs when a wallet owner fails to back up a seed phrase and later loses access to the device holding the private key — at which point the funds are unrecoverable, since self-custodial wallet providers do not hold seed phrases on behalf of users.

River's 2025 Bitcoin Custody ReportRiver's 2025 Bitcoin Custody Report

River’s 2025 Bitcoin Custody Report

Exchange failures add another dimension. Mt. Gox’s collapse involved roughly 740,000 BTC, though some were later recovered through a rehabilitation plan. One of the most high-profile individual cases involves Welsh IT engineer James Howells, who discarded a hard drive containing private keys to 7,000–8,000 BTC in 2013. The drive ended up buried in a Newport, Wales landfill, and in January 2025 the High Court dismissed his legal challenge to excavate the site, ruling it had no realistic prospect of success. At current prices, the lost cache is worth close to half a billion dollars.

What It Means for the Market

For long-term holders, the dormancy and loss data reinforce a scarcity argument that goes beyond Bitcoin’s hard cap. The estimated range of 2.3 to 7.8 million lost BTC comfortably exceeds the combined holdings of Bitcoin ETFs and corporate treasuries, which together total approximately 2.2 million BTC — a fact rarely highlighted amid coverage focused on ETF inflows and institutional accumulation.

The debate is unlikely to be resolved soon. Burn-address proof covers only a tiny fraction of estimated losses. Dormancy metrics remain probabilistic by design. The Patoshi-era coins continue to sit unmoved. Satoshi’s observation that lost coins benefit remaining holders may well hold true — but the actual scale of that effect depends on figures no analyst has yet managed to definitively confirm.


Source link

Franklin Templeton Files ETFs That Turn Stock Dividends Into Bitcoin Exposure – NFT Plazas Franklin Templeton Files ETFs That Turn Stock Dividends Into Bitcoin Exposure

0
Franklin Templeton Files ETFs That Turn Stock Dividends Into Bitcoin Exposure – NFT Plazas Franklin Templeton Files ETFs That Turn Stock Dividends Into Bitcoin Exposure


Franklin Templeton filed proposals with the U.S. Securities and Exchange Commission (SEC) on June 18 to launch two ETFs that combine U.S. equities with Bitcoin exposure. The two funds plan to use dividends from the underlying index stocks to increase their Bitcoin exposure, rather than reinvesting those dividends in the equities. The filings show that the funds could become effective as early as September 1, though a trading start date has not been confirmed.

How the Bitcoin DRIP ETFs Work

DRIP” stands for dividend reinvestment plan, a mechanism that uses dividends to buy additional shares rather than receive cash. With Franklin Templeton’s two proposed ETFs, this cash flow will not go back into equities but will instead be used to increase Bitcoin exposure.

According to the filings, both funds will initially start with an approximate weight of 95% U.S. equities and 5% Bitcoin exposure. The Franklin U.S. Equity Bitcoin DRIP Index ETF focuses on U.S. large-cap stocks, while the Franklin U.S. Innovation Bitcoin DRIP Index ETF targets companies in innovation sectors.

All regular and special dividends from the index stocks will be reinvested into Bitcoin at the start of the next trading session following the ex-dividend date. This could cause the Bitcoin weight to gradually increase over time, but this exposure cannot exceed 20% of the portfolio.

At each quarterly rebalancing, if the Bitcoin weight exceeds 5%, the index will reduce this weight back to 4.5%; if the weight is equal to or less than 5%, the fund will keep it unchanged. In the event that Bitcoin exceeds the 20% threshold between rebalancing periods, the index will adjust it back to 4.5% at the close of the second business day after the threshold is breached.

The pace of accumulation remains dependent on the dividend yield of the equity portfolio and Bitcoin’s price performance. A low dividend yield will slow the amount of capital moving into Bitcoin, while a sharp increase in Bitcoin’s price could cause this asset weight to hit the adjustment threshold sooner.

The Assets Behind Bitcoin Exposure

The Bitcoin exposure in the two funds will be created through various investment instruments, rather than solely through holding spot Bitcoin. According to the disclosure, the funds can generate Bitcoin exposure through Bitcoin Exchange-Traded Products (ETPs), including ETPs sponsored by an affiliate of Franklin Templeton; Bitcoin-linked futures and options contracts or Bitcoin ETPs; and depositary receipts representing ownership of Bitcoin. In some cases, the funds may also utilize a wholly-owned subsidiary in the Cayman Islands to gain Bitcoin exposure.

This point is important for investors because the funds’ performance may not perfectly align with spot Bitcoin price movements. Underlying product fees, derivative transaction costs, rebalancing timing, and tracking error could all create discrepancies.

Why the Structure Matters for Crypto ETFs

Instead of launching another spot Bitcoin ETF, Franklin Templeton embeds a Bitcoin accumulation mechanism into a portfolio with a U.S. equity core.

This structure may suit investors who want to gradually increase Bitcoin exposure within their existing portfolios but do not want to open crypto accounts, manage custody wallets, or decide on buy timing themselves. Bitcoin becomes a rules-based add-on allocation, rather than a separate investment requiring active management.

Dividends from the index stocks will be converted into Bitcoin exposure instead of being used to purchase more shares in the portfolio. This is the key difference compared to traditional equity ETFs or dividend reinvestment strategies. However, the index mechanism does not mean the funds will not make cash distributions to shareholders; the prospectus states that the funds still intend to pay out income and capital gains in accordance with applicable tax requirements.

Franklin Templeton’s Crypto ETF Footprint

Franklin Templeton managed approximately $1.78 trillion in assets as of May 31, 2026, according to the latest AUM report from Franklin Resources. This scale shows that the Bitcoin DRIP is a product proposed by a global asset manager that already has a significant presence in the ETF space.

The company has been operating the Franklin Bitcoin ETF (EZBC) since January 11, 2024. EZBC has total net assets of $358.90 million, according to Franklin Templeton data. Franklin Templeton has also launched ETPs tied to Ether, XRP, and a crypto index.

Franklin Bitcoin ETF (EZBC)

Franklin Bitcoin ETF (EZBC). Source: Franklin Templeton

The two DRIP funds expand this product line into a multi-asset structure. Unlike EZBC, which is designed to track the price of Bitcoin before fees, the new funds combine U.S. equities with a mechanism to accumulate Bitcoin from dividend cash flows.

Risks and Key Details Still Unclear

The initial Bitcoin weight is set at 5%, but it can increase based on dividend flows and price volatility before being adjusted according to the index rules. A sharp decline in Bitcoin will reduce the value of the exposure accumulated from dividends.

The use of Bitcoin ETPs, futures, options, and other investment structures also adds costs, valuation discrepancies, and tracking risks. These factors could cause the funds to track their reference indices less accurately.

The seed capital size, the prioritized basket of Bitcoin instruments, and implementation details prior to the trading date have also not been confirmed. This information will determine the total costs and the fund’s ability to closely follow the stated strategy.

What to Watch Next

The prospectus remains preliminary and may be updated before the filing becomes effective. The SEC has also made it clear that the agency has not approved or disapproved the securities offered in the filing.

Management fees, tickers, listing exchanges, and the VettaFi index methodology have not yet been finalized in the current filing. These details will determine the costs and how the two funds deploy Bitcoin exposure when hitting the market.


Source link

Popular Posts

My Favorites

Like a Dragon Series Comparison to Other Games

0
Like a Dragon series, formerly known as the Yakuza series, has carved out a unique niche in the gaming world. Its blend of...